Contractors All Risk Insurance (CAR)
Cover, Costs & How Underwriters Assess Risk
What is Contractors All Risks (CAR) Insurance?
Contractors All Risks (CAR) insurance provides protection against physical loss or damage to construction works during the build phase. It protects contract works, materials, and sometimes plant and temporary works against unforeseen events such as fire, flood, theft, accidental damage, and site incidents. Many policies include third‑party liability cover depending on structure and wording. Contractors all risk insurance is also commonly referred to as contract works insurance — the terms are often used interchangeably across the UK construction market, though technically contract works refers specifically to the works element of the policy.
Contractor’s All Risks insurance (CAR) is often treated as a standard procurement item, a ‘have to have’ that isn’t given a lot of thought in terms of what is actually being bought, and the cover that it provides. In reality, it is a structured assessment of delivery risk, and in the event of a claim needing to be made, it is important that the cover is adequate.
When reviewing an application for CAR, underwriters are not simply pricing a project; they are assessing how likely it is that something will go wrong – and how expensive that failure could become.
This comprehensive guide explains:
- What CAR insurance covers
- Who needs CAR insurance
- How pricing actually works
- How underwriters assess risk behind the scenes
- How contractors and developers can position projects for stronger outcomes
If you are actively arranging cover, you can arrange contact with our team at the bottom of this page, or simply send us a few brief pieces of information for a quote.
Who needs Contractors All Risks insurance?
CAR insurance is commonly required by main contractors, developers undertaking build risk, engineering contractors, infrastructure projects, and refurbishment or conversion schemes. Lenders and employers frequently require evidence of both CAR and performance bonds cover before work begins.
Main contractors
Project leaders requiring comprehensive site coverage to satisfy employer mandates before breaking ground.
Property developers
Build-risk bearers protecting their capital investments and providing necessary proof of cover to secure lender financing.
Developers often arrange CAR insurance alongside Latent Defects Insurance to cover both the build phase and the structural warranty period.
Engineering contractors
Technical specialists safeguarding complex structural and civil works against unforeseen physical damage or loss.
Infrastructure developers
Large-scale builders securing essential all-risk cover for major public or private civil engineering projects.
Refurbishment specialists
Renovation experts mitigating the unique structural risks involved in altering, upgrading, or converting existing properties.
Specialist subcontractors
Dedicated trades ensuring their specific on-site works, high-value installations, and materials are fully protected against unexpected physical damage.
What CAR Insurance covers (and what It doesn’t)
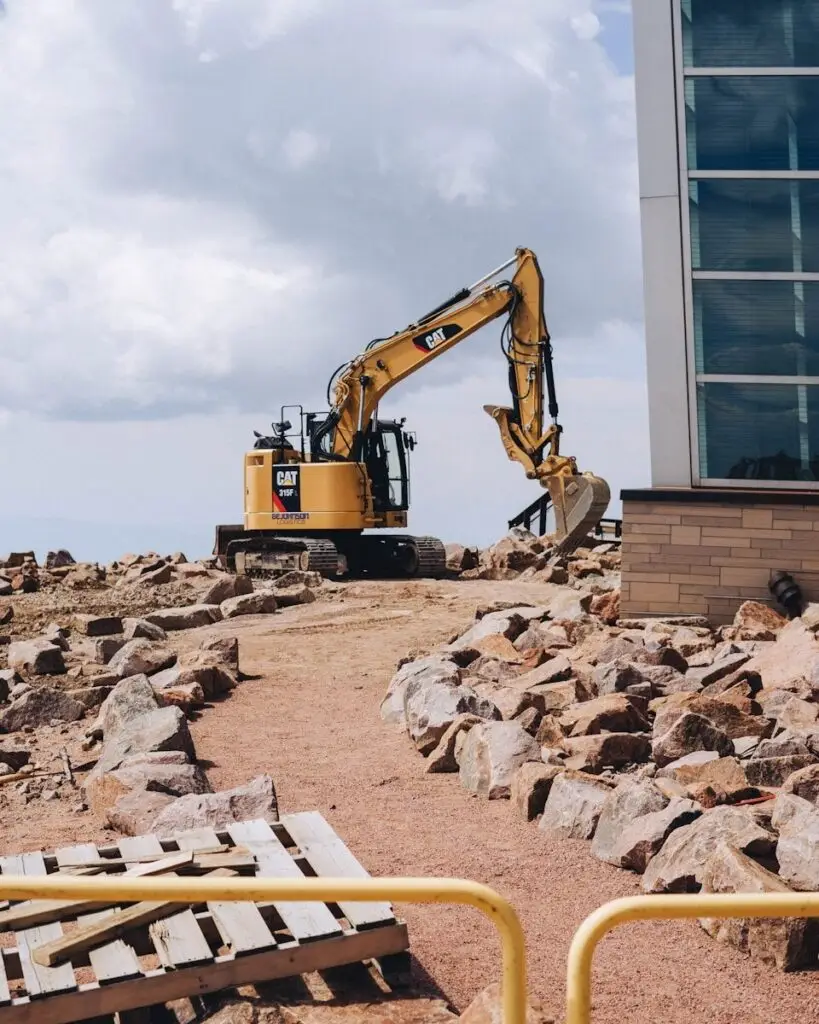
CAR insurance coverage typically includes:
- Contract works
- Stored materials
- Temporary works
- Debris removal
- Certain third‑party liabilities
Typical CAR exclusions to watch out for
Although exclusions vary from project to project and provider to provider, many common exclusions include:
- Poor workmanship (although resulting damage may be covered)
- Pure design defects unless extended
- Wear and tear
- Known pre‑existing issues
How underwriters assess CAR risk
Key underwriting considerations
It’s important to put yourself in the shoes of the underwriter to properly understand why underwriting sometimes goes the way it does – positively and negatively. The most important considerations to measure a project against usually include contractor experience, procurement route, construction methodology, site controls, claims history, and overall project complexity. The underwriter is effectively asking: if something goes wrong, how severe will the loss be and how likely is recovery?
Insider view - How underwriters REALLY think
Underwriters are not just analysing technical drawings - they are assessing behaviour. They evaluate whether the team delivering the project understands risk. Strong submissions demonstrate control: clear responsibility matrices, realistic timelines, experienced contractors, and evidence of learning from previous projects. Weak submissions often rely on optimism rather than structure. Underwriters price uncertainty - and uncertainty is expensive.
CAR pricing drivers - What moves the premium
Key pricing drivers include financial strength of the contractor, complexity of build methodology, geographic location, fire risk exposure, subcontractor structure, and quality of technical oversight. Projects that clearly articulate risk controls and demonstrate experienced delivery teams often achieve materially improved pricing.
Contractors All Risks Insurance cost: What to Expect
Pricing depends on risk profile rather than simply contract value. Standard ranges are often between 0.2% and 0.6% of contract value, but projects with challenging ground conditions, basements, complex designs, or inexperienced delivery teams can see significantly different outcomes.
Typical pricing influence (Illustrative)
Lower Risk Indicators
- Experienced contractor with repeat project type
- Strong site security and fire controls
- Clear procurement structure
Higher Risk Indicators
- First-time developer or contractor scaling rapidly
- Complex basement or high-rise construction
- Tight urban logistics or challenging ground conditions
Claims - What happens if something goes wrong?
If something does go wrong on site, the first step is simply letting the insurer know what’s happened. From there, they’ll usually ask for a brief summary of the incident and whatever you have on-hand to submit – a few photos, notes from the site team, and/or a short timeline of events.
An adjuster may get involved to understand the extent of the damage, and once they’ve reviewed everything, the insurer confirms what’s covered and what needs to be repaired or replaced. The process moves more smoothly when the facts are clear and the information is organised, and in most cases, the claim progresses steadily once everyone understands the situation.
How we approach Contractors All Risks Insurance
Our approach focuses on understanding the project narrative, aligning cover with procurement strategy, accessing specialist construction markets, and structuring submissions so underwriters understand the risk in the correct context.
Contractors All Risks insurance should not be treated as a commodity purchase. Handled strategically, it reduces friction with lenders, improves underwriting outcomes, and protects project viability during the highest risk phase of delivery.
CAR Insurance vs Public Liability – Key differences
Public Liability covers injury or damage to third parties. A contractors all risk policy covers the project works themselves. It’s important to note that these policies complement each other and should be structured together. Design-and-build contractors should also consider Professional Indemnity Insurance alongside their CAR policy to cover design liability.
CAR Insurance and JCT contract requirements (UK)
Many UK construction contracts reference insurance obligations under JCT frameworks. Contractors all risk UK requirements include aligning with contract insurance clauses, as well as joint-names requirements, reinstatement values, and contract works definitions. Misalignment between contract obligations and policy wording is a common source of disputes and delays. Projects requiring performance security alongside CAR cover should review Construction Surety Bonds & Guarantees.
Speak With a CAR Insurance Specialist
If you’re planning a construction project or reviewing your site insurance requirements, it’s worth speaking with us early in the process. Early engagement allows risk positioning before underwriting opinions form. It also enables alignment with lender requirements and contract structures, which improves negotiation leverage.
Earlier engagement with the Checkmate Warranty team typically leads to:
- Smoother underwriting conversations
- More competitive premium outcomes
- Better alignment with JCT or lender requirements
- Clearer communication of your project’s risk controls
Frequently Asked Questions
Our dedicated CAR specialists have compiled the questions most commonly fielded regarding CAR and related topics.
Generally, poor workmanship itself is excluded from the cover. However, if that poor workmanship results in subsequent accidental damage to the project, that resulting damage may be covered. Pure design defects are also excluded unless your policy is specifically extended to cover them.
No, they are separate but complementary policies that should be structured together. CAR insurance covers the physical project works themselves. Public Liability covers injury or damage caused to third parties during the build.
Not necessarily. Pricing is based on the specific risk profile of the project, not just the contract value. Underwriters look at factors like the contractor's experience, ground conditions, site controls, and project complexity. Standard rates often fall between 0.2% and 0.6% of the contract value, but challenging conditions can change this significantly.
The first step is simply letting the insurer know what has happened. You don't need a perfect dossier right away; just provide a brief summary of the incident alongside whatever you have on hand, such as a few photos, site notes, or a short timeline.
News and insights


